
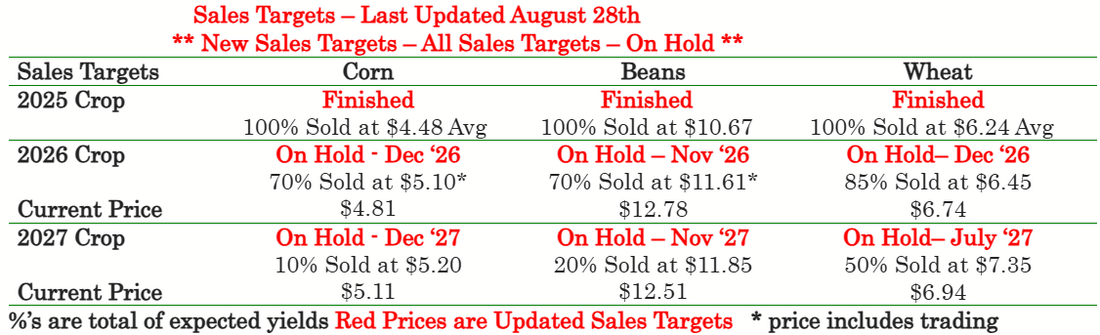
- Corn 1 ¾ to ½ lower
- Soybeans 6 to 8 lower
- Wheat 4 ¼ to 1 higher
- Basis Flat/Higher
- Live Cattle 123 lower (225.15)
- Dow Jones 230 lower (51,702)
- Crude Oil 115 higher (95.28)
- Feeder Cattle 243 lower (338.60)
Another depressing day of trade saw bean prices fall despite the market finally getting confirmation that China was back as a buyer in the morning sales report. Corn was also lower despite new 4-year highs in the EU corn markets while wheat clawed out modest gains. Harvest pressure continues to be part of the sales volume, but the funds continue to trim their once record long bean position as losses mount and patience wears thin after the recent price collapse. With the momentum clearly in the bears favor, prices have fallen in all three markets to important technical support at the old launching pads for the August rally, but any further weakness will turn the weekly charts uglier at a time when the bulls desperately need some positive news.
News and Notes:
- Harvest progress continues to move along quickly with dry conditions and summer like heat for the Midwest before a return to normal temperatures with increased rain chances return over the weekend. SA forecasts remain consistent and non-threatening as their planting progress continues at a record pace. It is rare for an October weather story to develop in SA unless the crop cannot get planted.
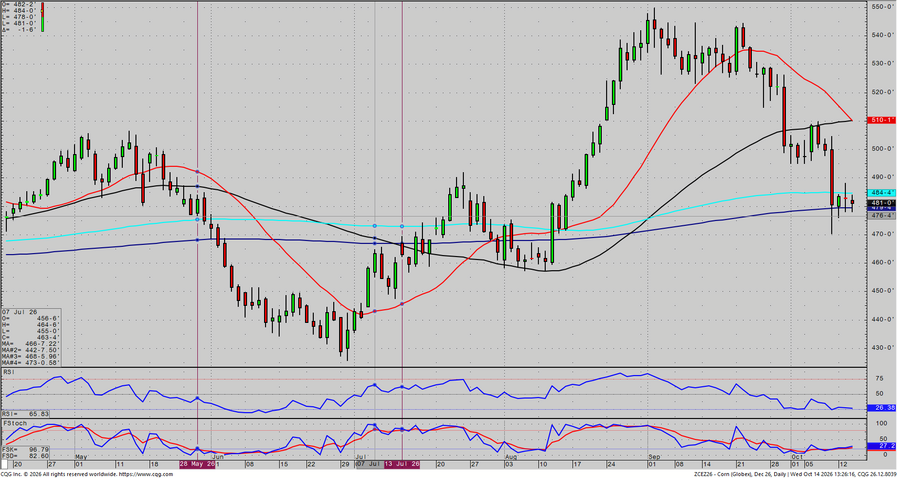
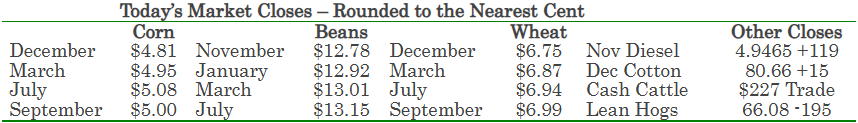
- The December daily corn chart is on Page 2 and shows corn continues to test the 200-DMA (black line) while also failing to close over the 100-DMA (blue). Since the release of Friday’s report, the price range from $4.78 to $4.84 has traded everyday with $4.80 the 200-DMA price. Despite the massive fund selloff into last Friday’s close, they have added roughly 50 MBU to their net long position this week. If support fails, the next downside target would be the $4.60 area. Today’s close was $4.81
- China was announced as a buyer of 17 MBU (8 cargoes) of beans this morning after a 2-week break from any purchases. There has been no news about US/China trade negotiations or follow up from the meeting in Washington. China has now fallen behind the pace to fulfill their 25 MMT pledge of buying US beans in 2026. The other problem is that the additional $17 billion in other ag purchases that was pledged earlier this year. US corn, even after the price break, is not profitable to import into China. Brazil and Argentine corn are cheaper despite skyrocketing freight rates.
- US harvest progress picked up last week with beans coming in at 46% complete (up 2% from last week) while corn remains behind normal pace at 33% (+10%). The late September and early October rain are making this the slowest harvest since 2019. Yield reports remain highly variable with reports from Nebraska’s corn is just 26% (55% average) which will mean that the massive USDA yield increase will be confirmed or refuted over the next few weeks.
- The average fall insurance revenue prices are $4.9340 for corn and $12.87276 for beans.
- Cotton prices have put in a solid $3.50 + rally over the last 2-weeks and made 2 ½ week highs (79.91) in today’s trade. Today’s high is just 1.06 from the contract high.
- Before today’s losses, the cattle markets had been on a nice run with Nov feeders making new 3-month highs (342.50) on Tuesday and $37 above the lows from the border re-opening and President Trump’s pledge to lower beef prices in August. Early week cash cattle trade has been reported at $3-$4 above last week. Dec cattle futures have had less of a rally but made new 2-month highs (227.60) on Tuesday.
The market trends have definitely changed as we are now seeing higher openings based on bullish news dissolve into daily losses with no buying conviction on even the smallest rallies. Farmers are selling the bushels they cannot store to provide overhead pressure, but with not large speculative or end user appetite at these discounted prices, the markets need to find a jolt or more fund selling is probable. Patience for published harvested yield reports and the November USDA yield update are the only things the market has to offer currently. If China continues to be a small and unenthusiastic buyer, the markets will not be able to rally. There will be no report on Thursday.
December Corn – Daily
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.