
- Corn 6 ¼ to 3 ¾ lower
- Soybeans 31 ¼ to 20 ¼ lower
- Wheat 15 ¼ to 16 ½ lower
- Basis Flat/Higher
- Live Cattle 105 lower (217.83)
- Dow Jones 246 lower (51,913)
- Crude Oil 8 higher (92.49)
- Feeder Cattle 305 lower (331.88)
Today was all about China not dropping the 10% tariff for private purchasers on US soybeans after other weekend news was supportive of the trade meeting. The tariff that was dropped only applies to China’s government buyers and does not include their private companies who process the beans. Once beans started their sharp descent, the corn and wheat markets were forced to follow despite escalation and heavy bombing of Russian infrastructure by Ukraine over the weekend. All three daily, weekly, and monthly charts took a hit today but did find buying support from end users as many bean processors were forced to raise basis bids to keep beans coming in as demand and margins for meal and oil remain strong. The US trade team is expected to put out a trade meeting fact sheet this afternoon, so Turnaround Tuesday will be interesting heading into Wednesday’s USDA Quarterly Stocks report that is expected to show tighter stocks than the June report.
News and Notes:
- The US WCB weather did not get much attention during the trade meeting, but it is excessively (and in some areas record) wet with cobs and bean pods falling to the ground with some fields seeing beans germinating inside the pods. This problem is not isolated as it covers a large area of the Dakotas, eastern Nebraska, western Iowa across in Minnesota. The forecasts call for more rain for the next 7-10-days with no meaningful dry pattern for another few weeks. If it quit raining today it would still take several days for enough drying of the ground to support the machines. This is another problem that will trim away at the margins for final yield. The ECB continues to see harvest progress with highly variable yields and very few reports of above average yields. Southern Hemisphere weather continues to follow the super El Nino pattern with hot forecasts for Australia and too much rain for S Brazil and Argentina. The lower Northern Hemisphere yields put significant pressure on normal to record yields from all major producing Southern Hemisphere countries.
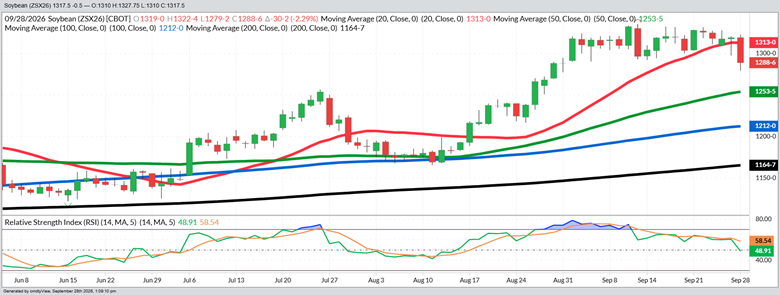
- The daily November bean chart is on Page 2 and shows the damage done by today’s collapse through the 20-DMA (red line) for the first time since mid-August. The plateau that held prices in a tight range from $12.90 to $13.30 for all of September has been violated and the daily chart will need to see a close back over $13.15 to restart the bullish trend. The RSI is approaching the level where the market started the massive rally from late August into early September.
- The weekly crop conditions are expected to be little changed, but the important reading will be how much harvest has been completed and just how far behind the saturated WCB states are. Expectations are for roughly 18-20% of the corn crop to be harvested by Sunday night.
- Wednesday’s USDA Quarterly Stocks report will mark the last big news release for the month and also put an end to both the month and third quarter. Speculative fund position squaring is expected to be part of the daily volume until after the report. The report is usually not a big deal, but several analysts point to the unusually strong basis levels that could be showing the USDA overestimated last year’s yield by 180-200 MBU and that mistake will be corrected in the “Disappearance” column.
- Diesel and crude prices were sharply higher overnight on the US rejecting Iran’s hollow cease fire proposal but fell back near unchanged by the end of the day. The rejection was expected but all markets sensitive to the war and political headlines remain overly sensitive to all developments.
The Chinese tariff decision does not change what was agreed upon last week as China is still going to end up buying the 25 MMT of beans that was agreed upon in the May meeting while adding another $15-$17 billion in other US exports, including corn and wheat. The entire purchase package is expected to be completed by year end with the enforcement mechanism being a return to the old much higher tariff structure that sent China’s entire economy into a serious recession for the last 18-months. The US and China agree on many more issues than they have in years and if just the Chinese government imports the bushels ,it will not have any effect on the totals purchased. The Chinese imports are expected to be for corn, beans, wheat, sorghum, and cotton to name just the big markets.
Sales Targets
Corn
Beans
Wheat
Cotton
- 2025 Crop Finished Finished Finished –
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg –
- –
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26 –
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45 –
- Current Price $5.22 $12.88 $6.88 –
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27 –
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35 –
- Current Price $5.24 $12.57 $7.10 –
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
November Beans - Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.22
- March $5.36
- July $5.46
- September $5.20
Beans
- November $12.88
- January $13.02
- March $13.12
- July $13.24
Wheat
- December $6.88
- March $7.02
- July $7.10
- September $7.17
Cotton
- – –
- – –
- – –
- – –
Other Closes
- Nov Diesel 4.4878 +257
- Dec Cotton 82.82 +11
- Cash Cattle $225 Offer
- Lean Hogs 78.48 +25
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.