
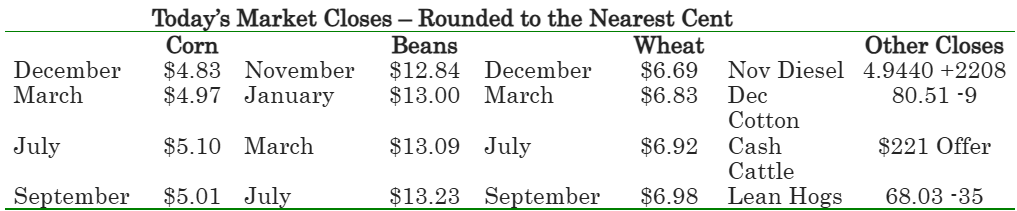
- Corn ¼ to ¾ lower
- Soybeans 4 to 6 lower
- Wheat 2 ¾ to 3 ½ lower
- Basis Flat
- Live Cattle 23 lower (226.38)
- Dow Jones 159 lower (51,947)
- Crude Oil 48 higher (94.22)
- Feeder Cattle 8 lower (341.03)
A lack of news led to a lack of interest which allowed the markets to drift on both sides of unchanged to finish with modest losses in low volume. China remains absent from the daily export sales report and has been extremely unresponsive to trade promises since the end of the US/China trade meeting in early September which has added even more problems to the recent bearish USDA report numbers. With US harvest speeding along and harvest keeping all rallies in check, even the bullish announcement from the EPA on small refinery exemptions and new contract highs in the European grain markets, the early rally attempts failed to gain traction. The rest of the week has no scheduled release of important news, but the daily export reports will remain important to judge China’s import intentions.
News and Notes:
- Hot and dry will stay around for most of the Midwest until the weekend when a more seasonal temperature pattern moves in with better rain chances. A cold snap is not expected to forecast until very late October and by then it will not affect yield. SA weather remains a split between a dry leaning central and northern belt while S Brazil and N Argentina. US harvest will move quickly for the next week with beans past 75% and corn past 50% by next week’s harvest progress report. Today’s progress is expected at 50% and 40%, respectively.
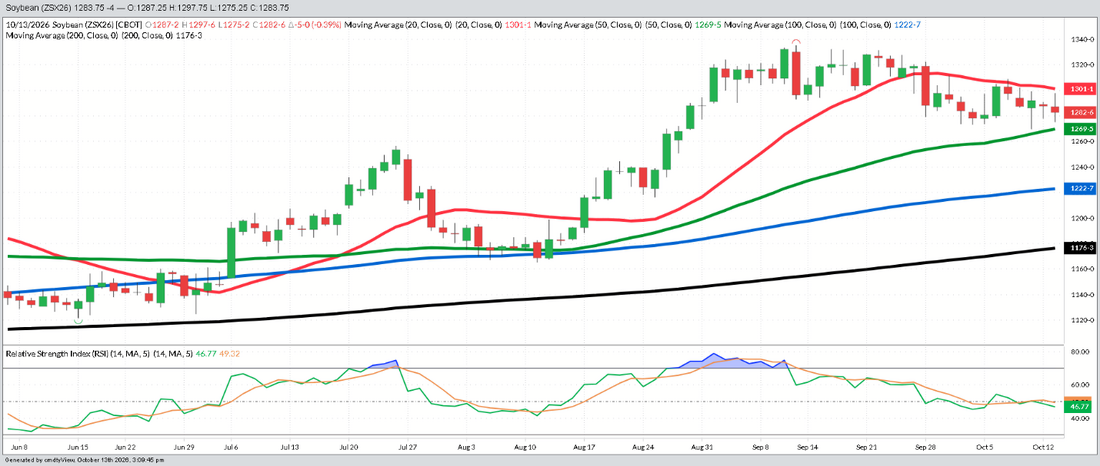
- The November daily bean chart is on Page 2 and shows the ongoing 2-week consolidation between the 50-DMA (green line) as support and the 20-DMA (red) as resistance. Considering how ugly the Dec corn chart has become the bean chart looks almost bullish by comparison. A daily and weekly close over $13.01 ¼ (20-DMA) is needed to reverse the current slow bleed bearish downtrend. The funds remain long over 1.2 BBU, which has seen a steady decrease in October.
- The world corn market remains hard to understand when you compare it to the US corn market. Europe’s corn crop is now expected to be half of last year’s production total which has rallied the EU corn price to new contract highs but has not been affected by the 70-cent +/- break in US futures prices. With the Black Sea export corridor closed, the European Union has no choice but to import US corn, but like China, their importers have not been active in the US export market. There is not enough corn in the world to allow the EU to avoid importing US corn. After the painful price break over the last 2 weeks, it is confusing no one is stepping forward buying the discount.
- The EU yield loss has been highly publicized this year, but Russia and China both lowered their yield estimates this week. The most interesting cut I saw was China cutting their bean stocks by another 25% this week and still are expected to need to import over 90 MMT (3.30 BBU) to meet their crush and feed needs. The US export pace should be strong this winter, but it is aggravating how slow it has been lately.
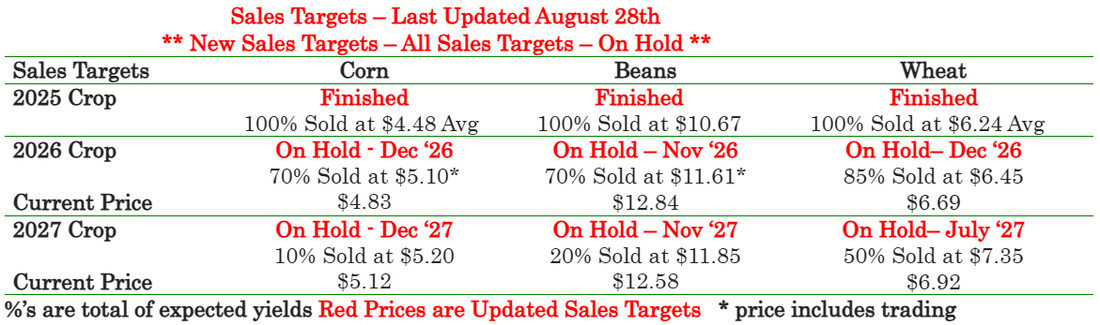
- The average fall insurance revenue prices are $4.94778 for corn and $12.88362 for beans.
- The EPA’s announcement that the same small refinery exemptions from last year briefly rallied bean oil and beans as the 1.76-billion-gallon credit will help increase blending and production to hopefully lower diesel prices. Unfortunately, diesel futures rallied over 20-cents a gallon today as any hope for a Ukraine/Russian energy infrastructure ceasefire ended.
The doldrums have settled over the markets and farmer attitudes after a tough 2 weeks with little bullish news to offer much resistance to bearish indifference. The world has a production and logistic problem, but the USDA bought the end user community some time with the recent bearish revisions. Harvest pressure will continue through the week but even when harvest nears the end and storage fills up, the market will need to see consistent demand from China to move higher.
November Bean – Daily
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.