
- Corn 3 ½ to 2 lower
- Soybeans 2 ½ higher to ½ lower
- Wheat ¼ lower to 3 higher
- Basis Flat/Higher
- Live Cattle 535 lower (220.95)
- Dow Jones 594 lower (51,918)
- Crude Oil 212 higher (104.12)
- Feeder Cattle 870 lower (337.78)
Another bearish week that started with the Brazilian election shocker and ended with the potential resumption of Black Sea trade from Russia, saw prices fall further to end October. Ongoing US harvest pressure continued with basis rising to coax bushels from farmers despite the recent bearish price trends. The bulls are hopeful the new month and the end of US harvest will stabilize markets with the USDA reversing their September yield increases while the bears realize momentum is on their side and world weather and the world political landscape are currently more bearish than bullish.
News and Notes:
- With US harvest moving into the home stretch, US weather will become less important. Harvest remains active with occasional rain slowing down Midwest progress. SA weather continues to be mostly non-threatening with quick planting progress in Brazil. It is too early for the market to fully discount or add significant premium for the current SA weather picture.
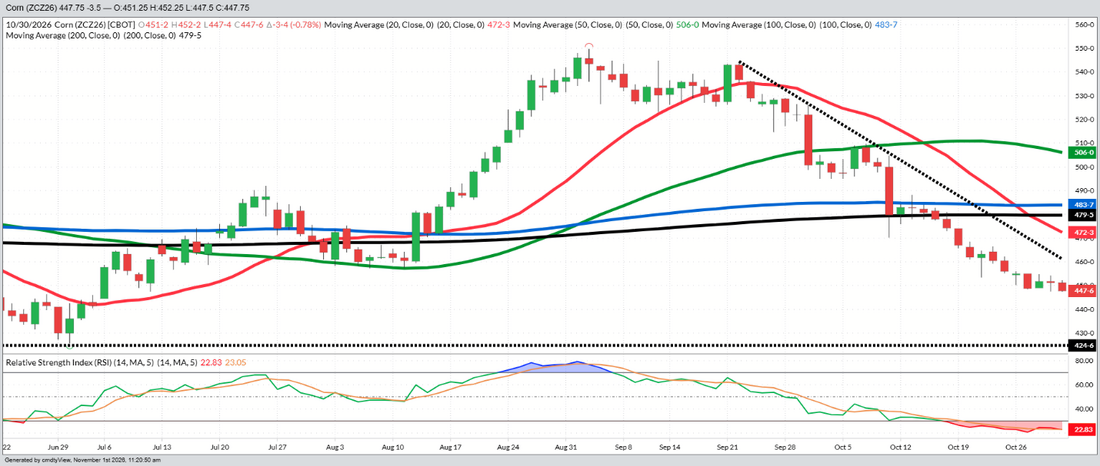
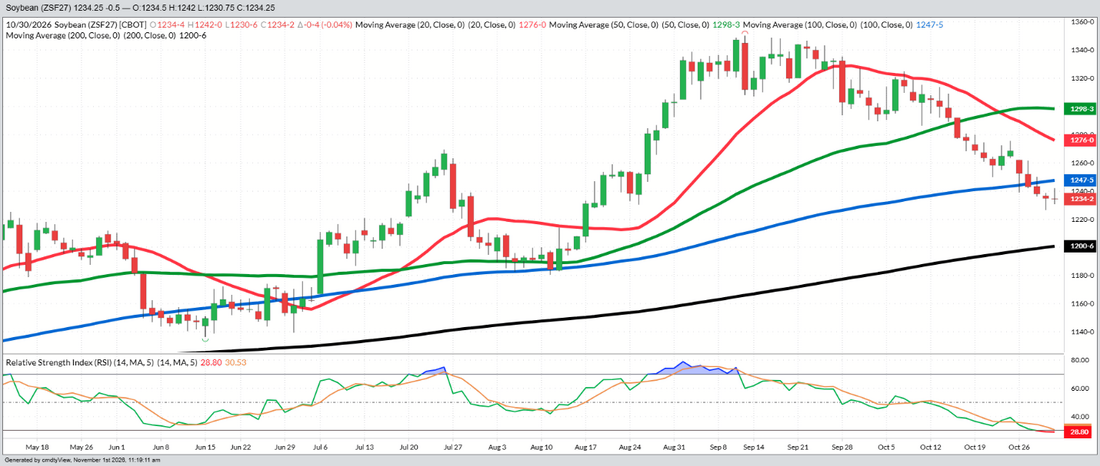
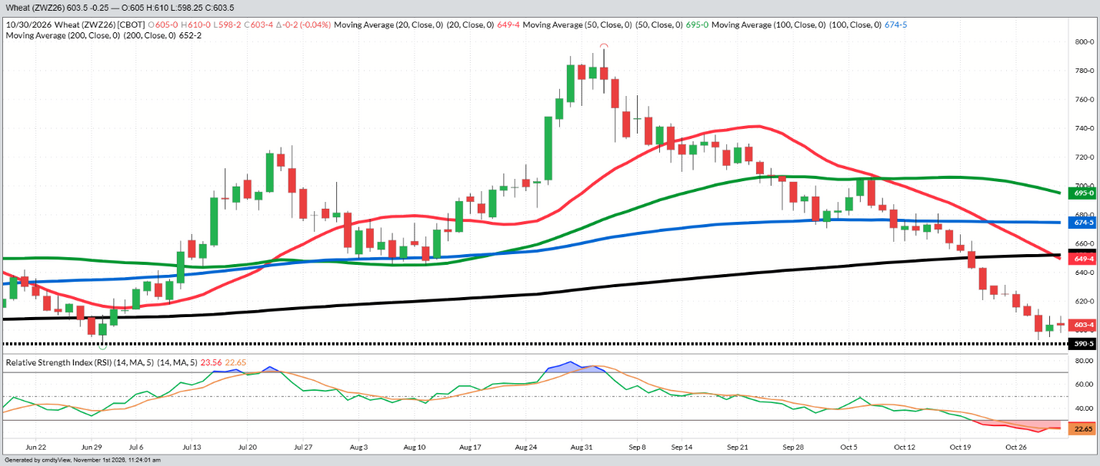
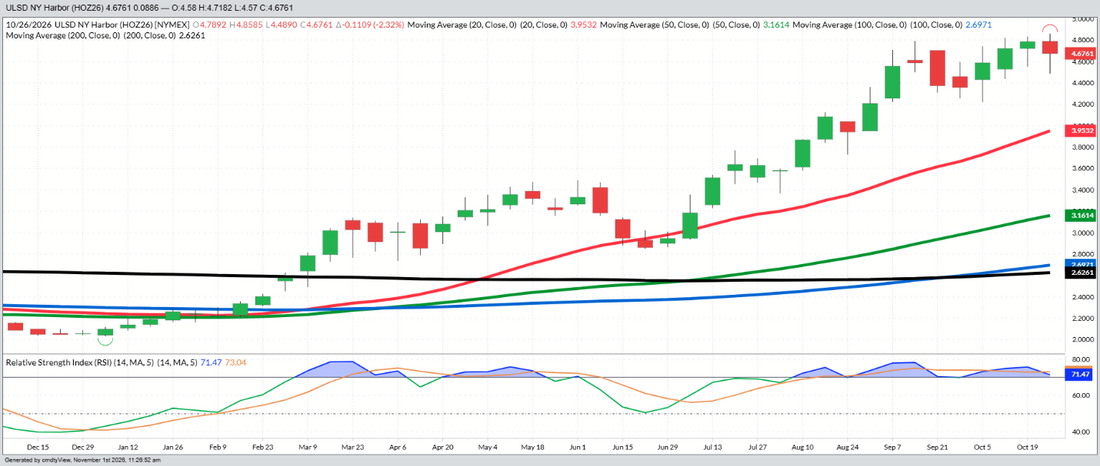
- The daily December corn, November bean, and December wheat charts are on Page 2 and show the carnage of the last 2-months as the USDA and other news forced the funds to abandon once record long positions in a massive selloff. The funds are now long only 280 MBU of corn (2.200 BBU in late August), 1.02 BBU of beans (smallest in 10-weeks) and short 380 MBU of wheat (largest short in 4 ½ months). The daily, weekly, and monthly technical picture is terrible in all three as all grain gains of the last 4-months have been erased while beans are $1.40 below the late summer highs. The weekly diesel chart is on Page 2 also and shows the comfortable range from $4.60-$4.90 that developed in October.
- After all the brutal market action in September and October, we are getting questions about what it will take to make prices put in a meaningful rally. Any sustainable rally must start with demand, a lot of it. China continues to pick around the edges with decent weekly bean purchases and world bio-fuel margins are still record high, but it has not been enough to reverse the losses. The world markets need to know the size of the US crops and if there is a legitimate chance the Black Sea will re-open. Until then, the reality of the bearish supply shock and no SA weather issue, will keep rallies in check.
- After last week’s complete blindside upset in Brazil’s Presidential election, Tuesday’s US election outcomes cannot be taken for granted by the current polls showing the Democrats riding the Affordability and anti-data center wave to retake the House and potentially the Senate. Partisan gridlock will be in place for the last 2-years of the Trump administration. A new Farm Bill and any hope of modernizing the USDA are unlikely to gain any traction.
- Russia/Ukraine escalated their attacks on energy and shipping infrastructure over the weekend. Cease fire/peace negotiations between both sides are still scheduled in 2-weeks, but signals from both sides do not show either are ready to concede anything. The US/Iran war will be impacted by Tuesday’s US elections as President Trump said he would resume attacks after the election.
- The final October average insurance revenue prices are $4.76 for corn and $12.64 for beans. The February revenue insurance averages were $4.62 and $11.09 which means any insurance payment based on revenue loss will favor beans unless there was significant yield loss. Please check with your insurance agent to see if your coverage will payout out this year.
- Weekly Changes: Corn – 8 1/4 (Dec ‘26), - 34 1/4 (Nov ‘26), Wheat – 21 1/2 (Dec ’26), Crude + 85, Diesel -1109, Dow+476, US Dollar+145, Cattle-1018, Feeder Cattle-1035, Hogs-670, Cotton-237, Milk-6 (15.19).
The next 10-days will be the most news filled of the month with Tuesday’s US elections and then the November yield update on Tuesday November 10th. The USDA drew a line in the sand after their ultra-bearish corn yield increase in September and their subsequent defense of their findings, it would be a shock to see them lower corn yield by very much. There is no doubt the USDA has a well-deserved credibility issue, which will not be solved unless everyone in the industry puts enough pressure on them and our elected officials to bring the agency into the 21st century. Opening calls are mixed. Have a great Sunday.
December Corn – Daily
January Beans – Daily
December Wheat - Daily
December Diesel – Weekly
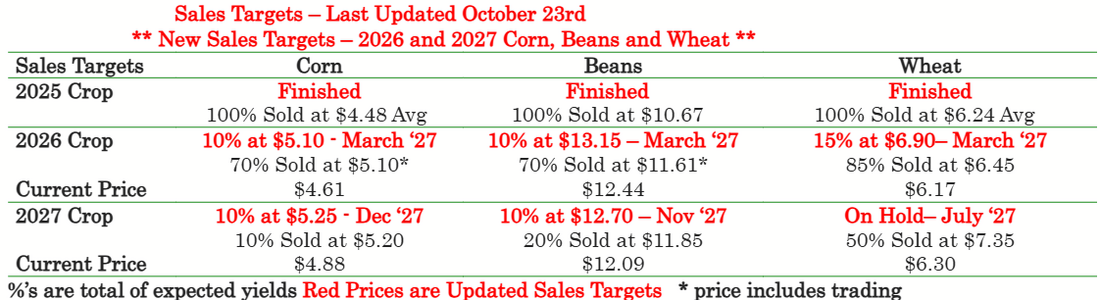
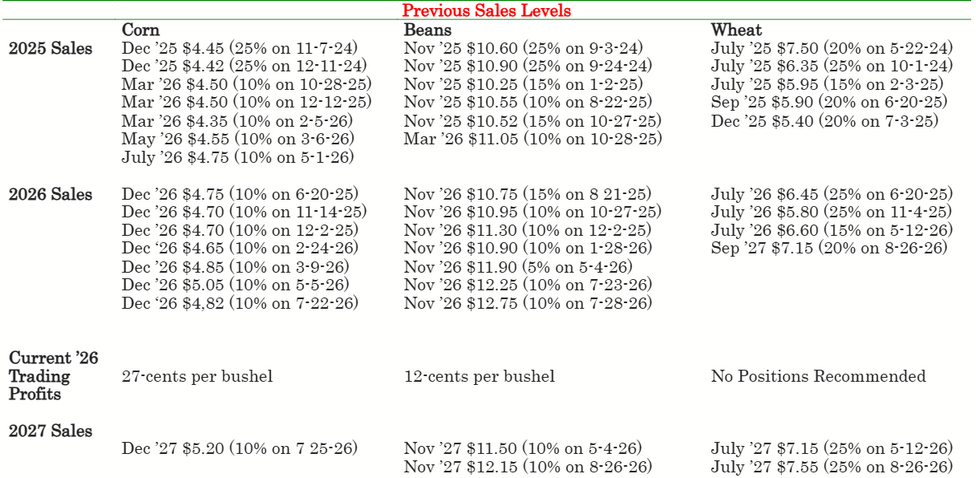
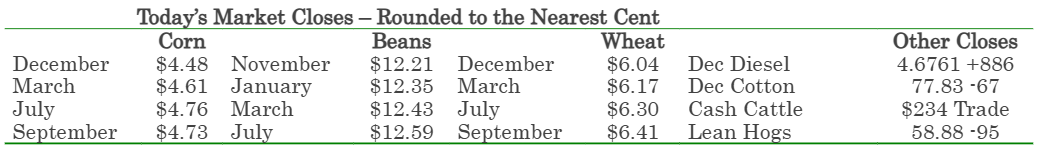
A Complete Overview of Current New Crop Market Conditions
Last Updated: 11/01/2026
Fundamentally
Technically
Short Term
Long Term
Volatility
Trade Rec
- Corn Neut/Bearish Bearish Neut/Bearish Neut/Bullish High None
- Soybeans Neut/Bearish Bearish Neut/Bearish Neut/Bullish High None
- Wheat Neut/Bearish Bearish Neut/Bearish Neut/Bullish High None
- Cotton Neutral Neutral Neutral Neutral Medium None
- Cattle Neut/Bearish Neut/Bullish Neut/Bullish Neut/Bullish High None
- Hogs Neut/Bearish Bearish Neut/Bearish Neutral Medium None
- Diesel Neut/Bullish Neut/Bullish Neut/Bullish Neutral High None
- Denotes positive change
- Denotes negative change
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.