
- Corn ¾ to 3 lower
- Soybeans 9 ½ to 6 ¾ higher
- Wheat ½ to 4 ½ higher
- Basis Flat/Higher
- Live Cattle 18 lower (217.28)
- Dow Jones 206 lower (51,632)
- Crude Oil 293 lower (89.68)
- Feeder Cattle 185 higher (333.75)
Indications from US port exporters that China has been asking for additional US bean bids helped stabilize prices after Monday’s meltdown with beans recovering about one-third of the losses while corn and wheat were mostly flat. Other than the cash source rumors, there was limited other news to trade ahead of Wednesday’s Quarterly Stocks report and the end of the month and end of the 3rd quarter trade. No diplomatic progress was announced in either war, but crude and diesel prices continue to trade at the lower end of the monthly range with both now 10-15% below the monthly highs.
News and Notes:
- The WCB is expected to get some relief from the recent heavy rains starting this weekend, but it will take several days for the ground to dry enough to support a combine. Harvest pace will remain no better than average over the next two weeks. SA weather continues to follow a wetter super El Nino pattern for S Brazil and N Argentina.
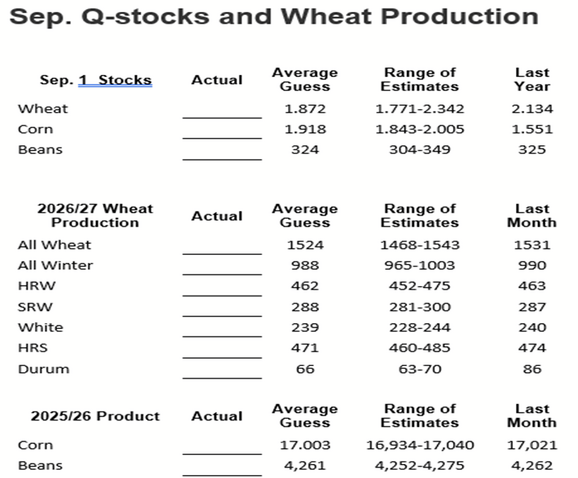
- The pre-report estimates for Wednesday’s USDA Quarterly Stocks report are on Page 2 and show the rather simple nature of the report. There will be n yield updates, just stocks numbers and some insight into any adjustments that were made. It is usually not a major market mover, but the USDA always has a habit of correcting prior mistakes without specifically saying that. The September 1st corn stocks number is the one I am most closely watching.
- The weekly crop conditions were unchanged (57 and 58), and harvest progress came in within estimates and in line with historic pace for both corn and beans. The one thing worth noting is the slow WCB pace and the extremely wet forecast they continue to face. This year’s crop has faced challenges at nearly every stage of development which makes projecting final yield more challenging, but the overall landscape is that lower corn yields and flat to slightly lower bean yields should be expected in upcoming USDA reports.
- Wednesday’s USDA Quarterly Stocks report will mark the last big news release for the month and also put an end to both the month and third quarter. Speculative fund position squaring is expected to be part of the daily volume until after the report. The report is usually not a big deal, but several analysts point to the unusually strong basis levels that could be showing the USDA overestimated last year’s yield by 180-200 MBU and that mistake will be corrected in the “Disappearance” column.
- With crop insurance claims expected to be larger than in any of the last 3-years, the recent breaks in the markets may want everyone to consider looking at locking in floors on any upcoming rallies through option strategies. With the October price averages setting the fall insurance price level, it is important to not let any strange event cut into the insurance price that you will collect. Please call us for details on how this can be accomplished within your budget and risk tolerance.
It has been a very frustrating last 7 sessions of trade as optimism surrounding the US/China trade meetings proved somewhat misguided as the meeting highs were posted an early last week with a steady decline in price unfolding since. Dec corn has traded as much as 30-cents off those highs; Nov beans were 52-cents off the highs while was 50-0cents off at today’s lows. The trade deal did not impress the bulls and President Trump and Sec Bessent’s statements that American farmer would love the new trade deal have not been proven accurate so far. Considering the Sep Quarterly Stocks report is not historically a big market mover, it seems odd that the funds would take a more neutral position when the Chinese continue to purchase beans and the US and China agree on more things now than in several decades on what should be addressed in the world. Wednesday’s report and the end of the month and quarter should allow the entire trade to refocus on the world shipping problems from two wars, US harvest weather issues and ongoing reports of highly inconsistent and disappointing US yields. One great trend that has been undefeated in the 2020’s is that prices posted higher highs than the late summer highs sometime in the October/November time frame in 5 of the last 5 years for beans and 4 of the last 5 years for corn. That is a great trend to help give us all a little more patience when the markets get frustrating. We will put out an overview of the USDA report after Wednesday’s 11 am central release to highlight the changes.
Sales Targets
Corn
Beans
Wheat
Cotton
- 2025 Crop Finished Finished Finished –
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg –
- –
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26 –
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45 –
- Current Price $5.22 $12.98 $6.93 –
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27 –
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35 –
- Current Price $5.22 $12.65 $7.13 –
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.22
- March $5.36
- July $5.46
- September $5.18
Beans
- November $12.98
- January $13.13
- March $13.21
- July $13.34
Wheat
- December $6.93
- March $7.07
- July $7.13
- September $7.17
Cotton
- – –
- – –
- – –
- – –
Other Closes
- Nov Diesel 4.5108 +167
- Dec Cotton 78.86 -400
- Cash Cattle $225 Offer
- Lean Hogs 79.38 +113
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.