
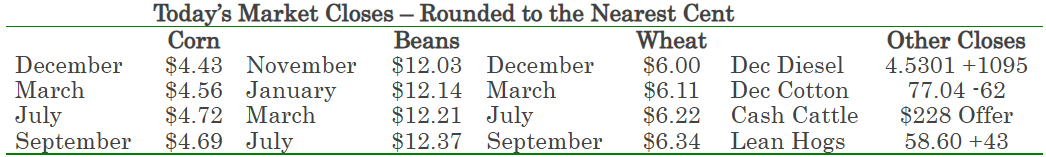
- Corn 5 to 5 ¾ lower
- Soybeans 1 ¾ to 8 ¼ lower
- Wheat 6 ¾ to 8 ¾ lower
- Basis Flat/Higher
- Live Cattle 155 lower (218.15)
- Dow Jones 175 lower (51,960)
- Crude Oil 50 lower (95.96)
- Feeder Cattle 390 lower (334.53)
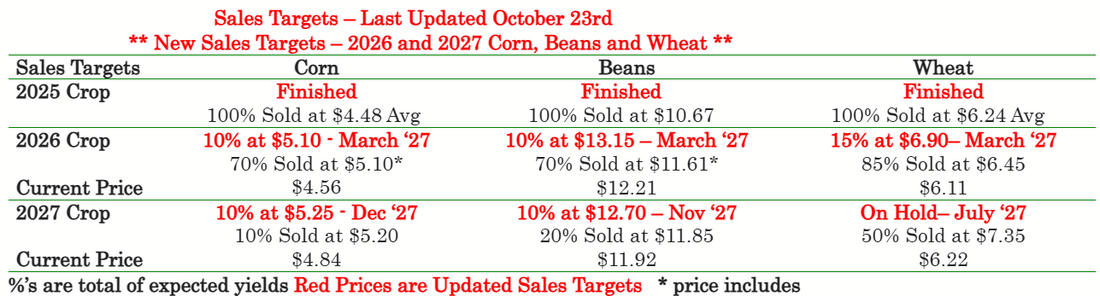
Fear remains the constant factor in recent trade as the funds are fleeing their net long bean position as their losses mount while the grain traders remain heavily on the sell side as the fear of the Black Sea shipping corridor re-opening continues to drive corn to new 4-month lows with wheat testing significant psychological support. Today’s election results will not have much if there is any impact on the ag markets, as the entire grain and soy complex landscape are crowded with bearish leaning news with no apparent bright spots emerging.
News and Notes:
- There are no domestic or world weather concerns which have allowed the bearish trends to dominate the news. SA weather will not become a market moving factor until Thanksgiving to early February.
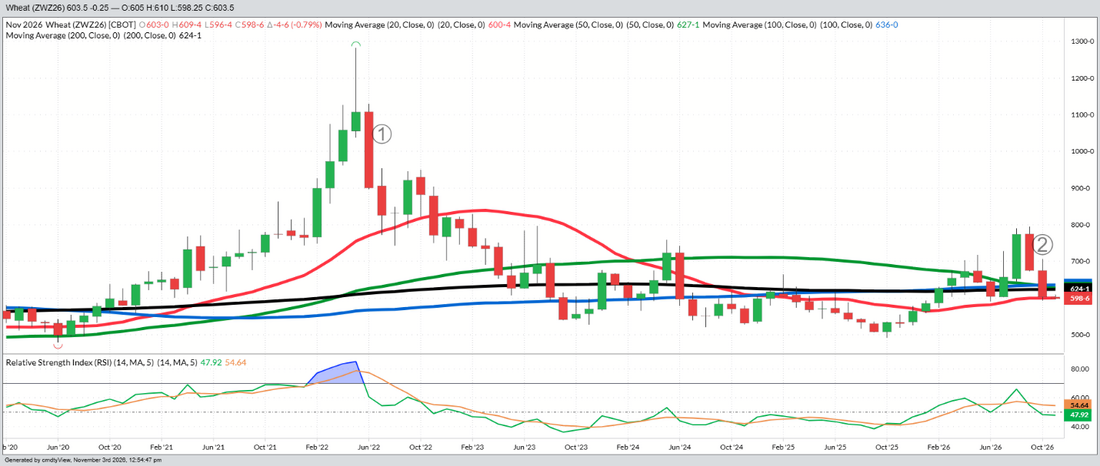
- The monthly spot wheat chart is on Page 2 and highlights then price collapse when the Black Sea export corridor initially opened in June/July 2022 (1) and what has happened to price (2) since the November 10th meeting with Russia and Ukraine to discuss reopening shipping. While the price loss in 2022 was larger, the percentage of loss to total price was roughly the same in the 25-30% range. The only weekly technical support that remains is the 20-DMA (red line) at $6 which was breached in today’s trade. Corn will not be able to rally without wheat finding a bottom. Coincidently, the monthly spot 100-DMA is the last layer of technical support and is also right at $6. December wheat holding $6 is very important as there is no underlying technical support until the low-$5 area.
- Last week’s open harvest window helped harvest speed along with corn harvest up to 74% (+14%) with beans advancing to 88% (+9%). Both paces are slightly behind the 5YA due to the wet start and downed corn in many of the WCB states. The US winter wheat crop was rated 44% G/E (50% expected), but initial condition ratings have little correlation to final yield. While we are harvesting, Brazil is busy planting with their total bean crop 53% planted (+13%) with their corn crop 63% (+5%) planted. Both of Brazil’s totals are slightly ahead of last year’s pace.
- Today saw more daily flash sales reported with Mexico on the board again today for 12 MBU of corn, 5 MBU of corn to S Korea and a small 5 MBU sale of beans to Unknown. The corn business is normal and expected and the bean purchase is not enough to move the needle.
- A footnote on my note yesterday about control of the Senate and house Ag committees. Senator Klobuchar (D-MN) is running for Governor of Minnesota and leading in the polls. The Senate Ag website is not clear who would be the ranking Democrat if the Democrats win the Senate. Rep Angie Craig will be the ranking Democrat on the House Ag committee.
- The final October average insurance revenue prices are $4.76 for corn and $12.64 for beans. The February revenue insurance averages were $4.62 and $11.09 which means any insurance payment based on revenue loss will favor beans unless there was significant yield loss. Please check with your insurance agent to see if your coverage will payout out this year.
Election day is always a busy and nerve-wracking day of news, but little of it will affect grain and soy price for eh rest of the week. There are opinions on what President Trump may or may not do regarding China trade policy after the election, but no one knows for sure. The scheduled peace negotiations on November 10th and 11th to reopen the Black Sea have put the grain trade in a state of panic while the bean collapse is much more tied to the funds holding a 1 BBU long when the grain markets collapsed. The funds were a great friend on the August rally and are an unbeatable foe in the 2-month-old collapse. The USDA “found” an extra 500 MBU +/- in the last 6-weeks, which normally would force a 40-50 cent market break instead of a $1 break. Always know what the funds are doing when you are making marketing decisions.
Spot Wheat - Monthly
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.