
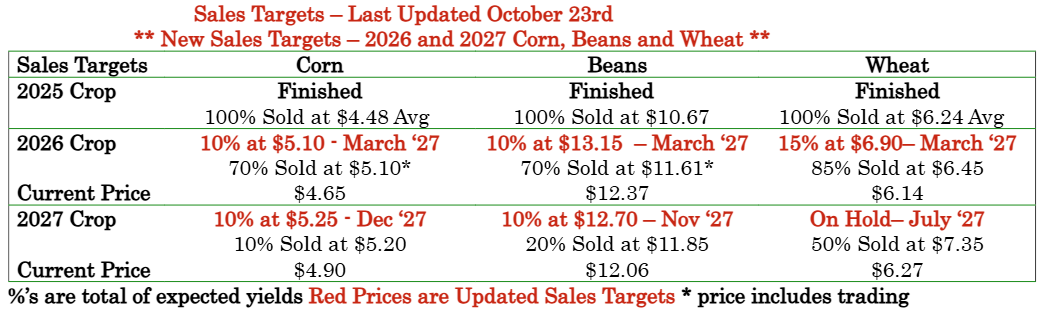
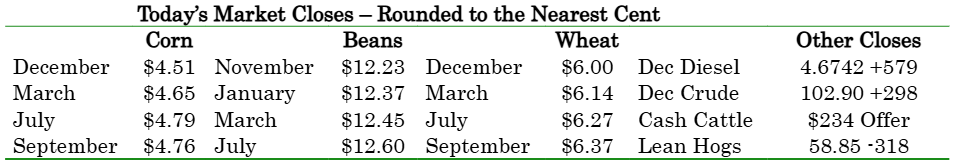
- Corn 2 ½ to ¼ higher
- Soybeans 6 to 7 ¾ lower
- Wheat 10 ¾ to 5 ¾ lower
- Basis Flat/Higher
- Live Cattle 383 lower (227.03)
- Dow Jones 33 higher (52, 621)
- Feeder Cattle 320 lower (346.83)
- Cotton 9 higher (78.15)
The markets traded mixed with corn scraping out very small gains while wheat was a double-digit loser after Russia announced they are re-opening the Kerch Strait for shipping for the first time since July. Russia will be providing naval escorts for any ships they send out through the Kerch Strait, but Ukraine has not agreed to a ceasefire despite multiple diplomatic efforts by leaders. Beans again traded higher early only to sell off into November futures first notice day to post another disappointing day of trade. There have been no daily flash sales to anyone this week which also added pressure to the beans.
News and Notes:
- The easiest way to describe the US, SA and world weather is that there is nothing to describe. It is all pretty normal and non-threatening. Super El Nino is intact and is forecast to hang around through early 2027, but so far it has done nothing to hurt world yield.
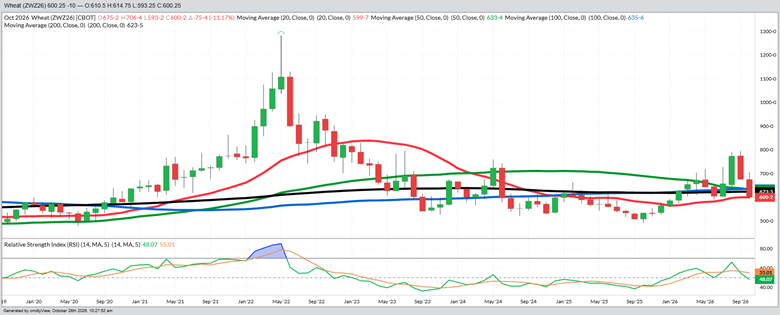
- The front month monthly wheat chart is on Page 2 and goes all the way back to just before Covid. The price of wheat has fallen below the price it was in the month before Russia invaded Ukraine as the trade reflects the recent sentiment that the Russia/Ukraine war will end soon and the millions of hostage bushels from both Russia and Ukraine will soon flood the market. The emotional reaction will be bearish when/if that is announced, but at these levels, it fundamentally would not make sense for wheat to fall much further. Wheat futures are priced as if those bushels are already in the system, which makes no sense. A complete end to the Russia/Ukraine war and a total reopening of Black Sea shipping capacity would be bearish and make a grain rally even more challenging into year end.
- Weekly ethanol production was 7 Mga better than last week and ahead of last year but the morning daily sales report featured no corn sales to anyone and no bean purchases by China. Thursday’s weekly export report is not expected to be overly impressive in any category.
- The Federal Reserve announced no change in interest rates today as the Fed typically defers ahead of the November election cycle. Inflation remains a problem, largely because of record diesel prices, but rate cuts will not build new refineries in Russia or the US, so it hard for the Fed to solve the inflation problem when interest rate changes are their only weapons.
- Election season rolls along and after the bearish upset in Brazil, Israel’s election was Tuesday and it is too close to call. Israeli citizens are pushing back against the current President Netenyahu, and the opposition party and candidate is not anti-war, but has a different strategy than the current administration. If the opposition party wins, the war with Iran will have less support in Israel. Of course, next Tuesday, we go to the polls with the Democrats forecast to retake the House and possibly the Senate. The last 2-years of Trump’s term will be complete gridlock with straight bi-partisan votes.
- The average fall insurance revenue prices are $4.7835 for corn and $12.6803 for beans. With only 2-days left, the averages will continue to move lower as both Dec corn and Nov bean prices are substantially below the current monthly averages.
Markets can bottom on a lack of news, but they cannot definitively rally without bullish news. All bullish news has been absent for 2-months as the excitement over the Chinese trade deal disappeared, the USDA ran a great rally off the road in just two reports and bearish world events continue to pop up. After first notice day for November futures and those contracts are sold or rolled, there is a potential that the new month will see harvest near completion to stop farmer selling and enough factual corn yield for the USDA to lower their corn yield number to a believable number in the monthly report. After the November report, there will not be another yield update until the report in January, which is a 2-month void of impactful reports, so time is running short for the bulls to build a story and a bullish trend into the holidays. There will be no daily comment on Thursday unless something crazy happens.
Wheat – Continual Monthly
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
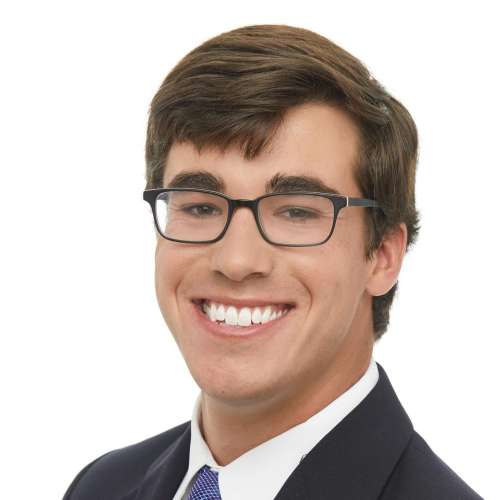
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.