
- Corn 10 ¾ to 7 ¼ higher
- Soybeans 19 ¼ to 22 ¼ higher
- Wheat 11 ¼ to 12 higher
- Live Cattle 398 higher (221.23)
- Dow Jones 279 higher (51,837)
- Crude Oil 18 higher (89.62)
- Feeder Cattle 665 higher (340.50)
An unexpected sharp drop in Iowa’s corn rating and US harvest falling behind pace helped rally corn back over $5 while beans rallied on Chinese cash interest and the forecast return of soaking rains on the WCB unharvested crop while wheat found buyers on escalation of Russian Black Sea attacks. After the sharp two-week decline, the markets were due for a bounce, but the bullish background information continues as the wars are affecting world grain logistics, the US crops remain under stress while Chinese demand is ongoing. While these factors should be enough to support prices, the bullish funds are still gun-shy about Friday’s USDA yield update after the bearish quarterly stocks report.
News and Notes:
- With harvest getting restarted in many areas with others still waiting, this week’s dry pattern will mean the combines will roll 24/7 until another rain system moves in late this weekend with a tropical depression expected to soak the Delta and southeast starting on Saturday. The ongoing wet weather problems showed up in the harvest progress as the off week pushed harvest behind the 5-YA. Crop quality problems continue to be reported with out of condition bushels needing to be mixed with stored bushels to pass inspection and avoid any dock fees. On top of the US problems, S Brazil’s forecast has significant rain totals for the next 3-weeks to further complicate their planting. The super El Nino pattern remains consistent in SA with N Brazil much drier than normal.
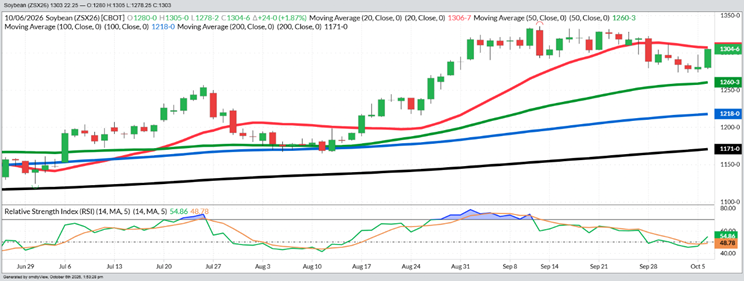
- The November bean daily chart is on Page 2 and shows today’s return to pushing back to both $13 and the 20-DMA (red line). After moving into oversold readings late last week, the funds and end users used that opportunity to re-position as the fundamental news turned more bullish to start the week. The funds are long roughly 1.15 BBU, which remains at the upper end of range they have held most of the growing season. Any drop in final US bean yield under 52.5 BBU, will set off a run to the Sep 11th contract highs at $13.35 ¼. Today’s close was $13.04 3/4.
- The cattle markets had been quietly working higher after the border crossing in New Mexico re-opened, but after testing technical support on Monday, the futures markets exploded higher today with cattle up $383 and feeders up $663. October feeder futures made new 2-month highs today.
- Early October crop ratings rarely cause much market reaction, but the weekly report showed Iowa’s corn ratings fell 2% and their bean crop rating fell 4% to pull the national ratings down 3% (54%) and 1% (57%). The states from Nebraska to Ohio that have been plagued by flooding rains lately were the hardest hit in the ratings. While it is hard to correlate late season ratings to final yield, if these ratings had been released a month ago, prices would be much higher and yield projections much lower.
- The average fall insurance revenue prices are $5.01437 for corn and $12.8694 for beans.
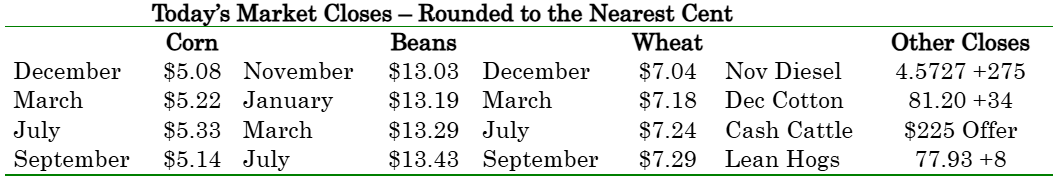
- Diesel futures fell to 5-week lows with the November contract trading down to $4.35 a gallon overnight before a sharp intra-day bounce pushed the price back over $4.55. Continue to use these breaks to top off your tanks.
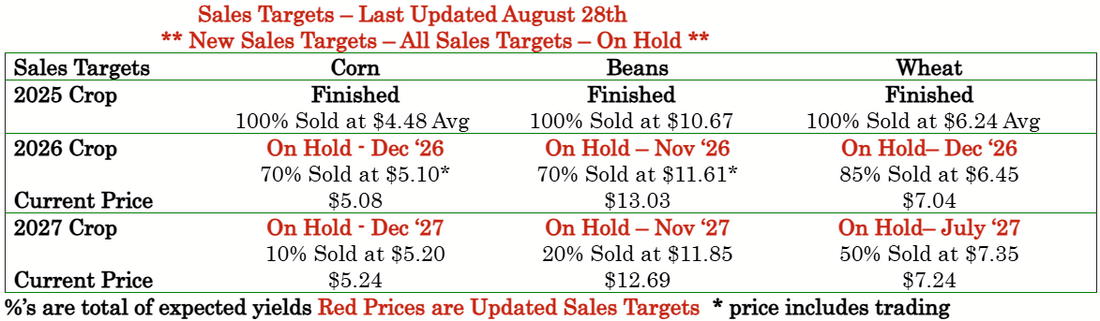
One interesting thing that the markets are dealing with today is that corn pushed back over $5, beans over $13 and wheat over $7. The big psychological numbers usually are surrounded by sell orders and for prices to cruise through them and close above them means farmer hedging stopped on the break. During harvest, the farmers are the largest sellers in the markets and if farmer hedging does not return, end user buying and potential fund buying on bullish news will hit little resistance. If President Trump’s campaign statement about China buying double their ag agreement is evenly partially true and the US harvest continues to struggle, support will remain at today’s lows. The short-term wild card is Friday’s yield update. If trade estimates are met for a modest reduction to corn yield and no change in bean yield, the market will remain choppy with an upward tilt. If the USDA cuts yield under 176 and 52.5 on Friday, both sides of the trade will have to quickly recalculate fair value and how to be positioned in a return of solidly bullish trends.
November Beans – Daily
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.