
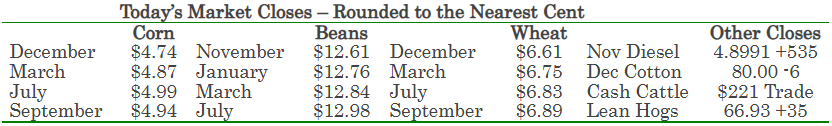
- Corn 3 ½ to 4 ½ lower
- Soybeans 1 ¾ to 3 lower
- Wheat 9 ½ to 6 lower
- Basis Flat/Higher
- Live Cattle 110 higher (228.35)
- Dow Jones 216 lower (52, 214)
- Crude Oil 344 higher (101.41)
- Feeder Cattle 5 lower (341.90)
The relentless hedge pressure and fund selling continued on Friday with a bad week getting worse as prices fell through significant technical support. With harvest pressure and fund liquidation the main selling volume last week, prices continued their descent back to the August lows as the trade digests the larger USDA yields and unimpressive Chinese demand. With harvest expected to move past 50% this weekend, the US harvest pace has quickly caught up over the last 7-10-days with inconsistent corn yield reports but ongoing consistently strong bean yields. South American planting and weather are not seeing any meaningful problems which leaves the bulls missing any major story to start a price climb out of this hole.
News and Notes:
- US weather has returned to seasonal fall temperatures but will continue to be dry for the next few weeks to advance harvest quickly. US harvest weather is no longer a concern. SA planting weather has been great in N Brazil but still a little slow in S Brazil and N Argentina due to heavy rains. There is no price moving world weather story.
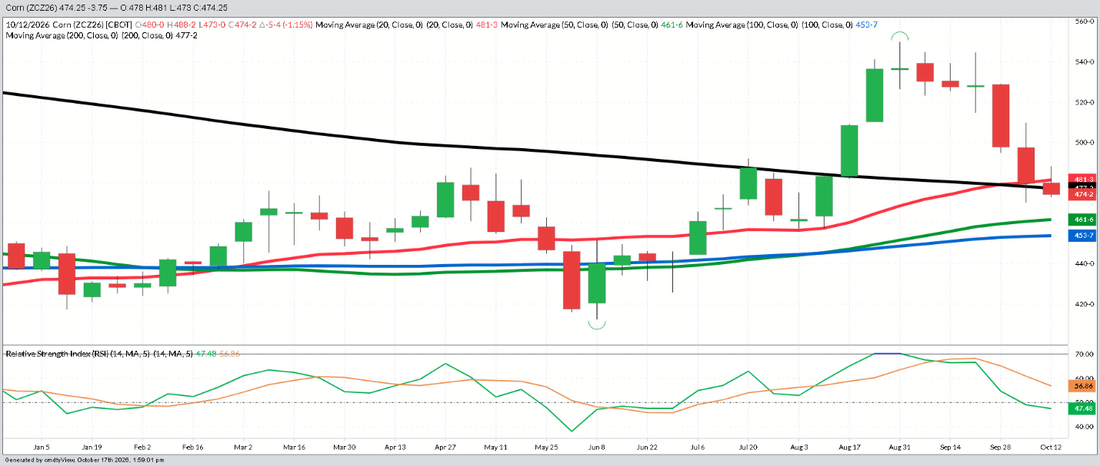
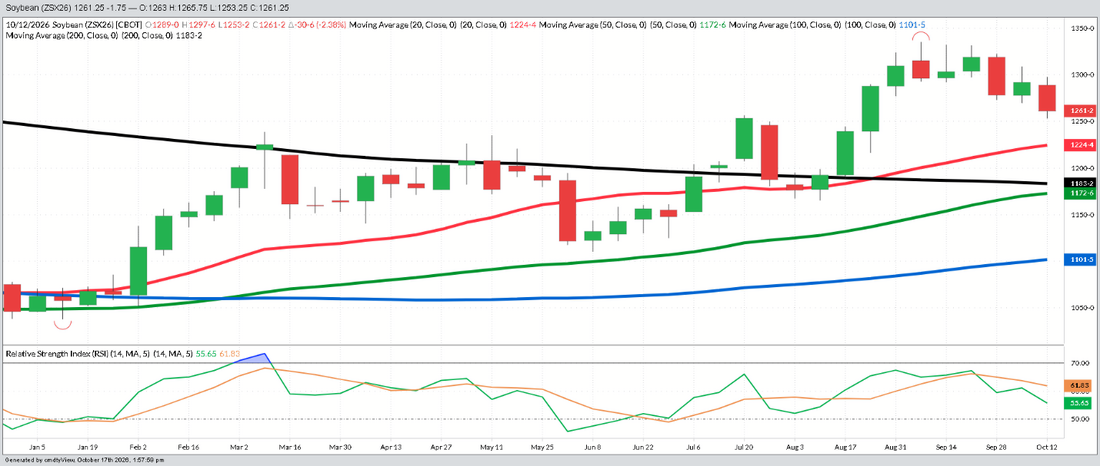
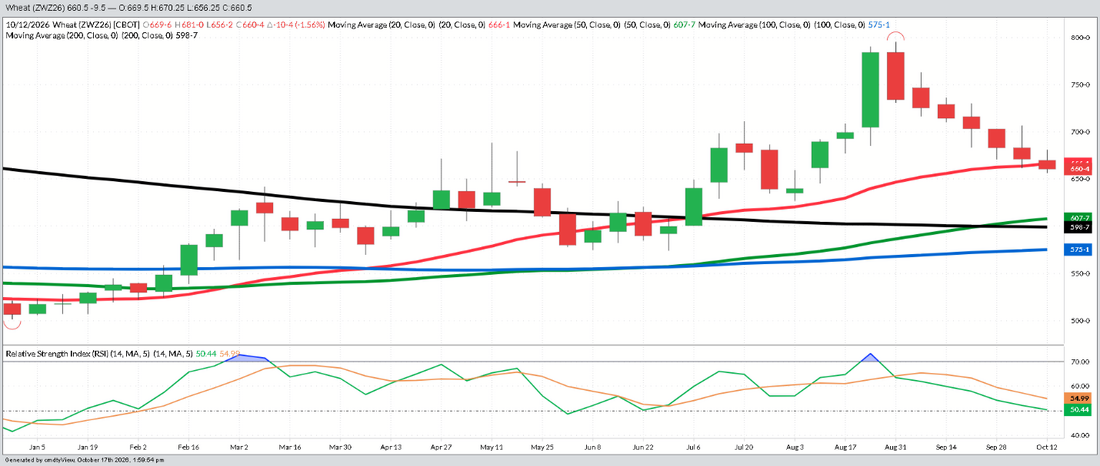
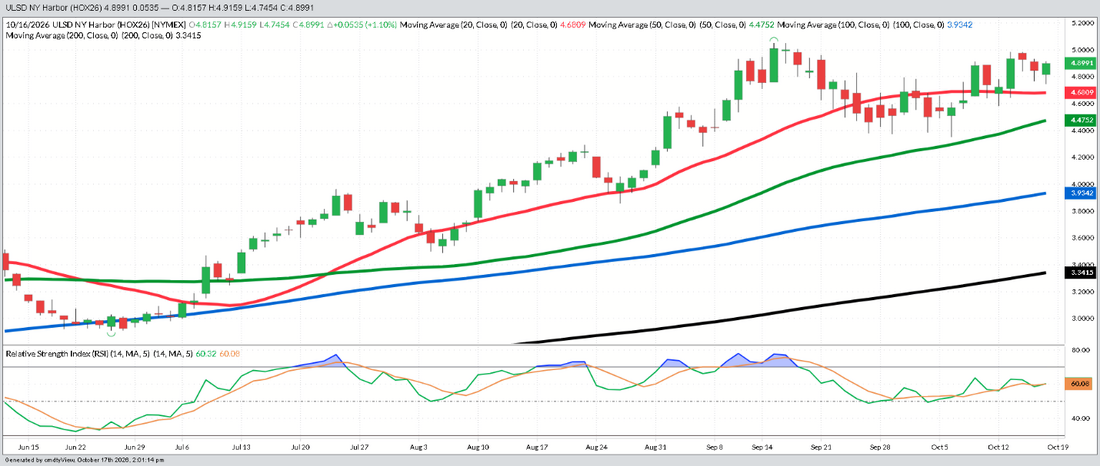
- It is no mystery how bad the daily charts look after the recent collapse, so I wanted to move to the weekly charts to see how much longer-term damage has been inflicted. The weeklies are not as bad, but both corn and wheat fell below the 20-DMA (red line) while corn also fell through the 200-DMA (black) to put the grains on the edge of forcing more technical liquidation. The weekly bean chart is still solidly bullish. The daily diesel chart shows the volatile trade between $4.48 and $5.00, as the infrastructure damage to Russia’s refineries continues to have a choke hold on record prices at the pump. The funds have substantially cut their net longs in the summer row crops in the last 6-weeks and are now long 1.2 BBU of corn, 1.08 BBU of beans and while adding to their short 200 MBU wheat position.
- Please take a few minutes to listen to the latest Helena FieldLink podcast where early season weed control and my thoughts on the post-USDA report trade and a look at other current conditions.
- Weekend escalation in the Ukraine/Russia war saw Ukraine release a massive drone attack on key Russian refining and energy locations in St. Petersburg, Russia. Expect diesel prices to move higher to start the week on this news. Russia is the world’s largest refiner and exporter of diesel, which is responsible for the record diesel prices. The Straits closure has a much smaller impact on diesel prices.
- The bean bulls had been desperately waiting on China’s return to the daily sales report and after a long dead period over the last 4-weeks, China came back in to buy US beans this week. Unfortunately, no one paid any attention as any rallies from the sales announcements were quickly sold.
- Basis levels remain unusually strong for harvest season as the price collapse has forced elevators and end users to offset some of those losses by increasing basis. Look at your basis levels for current and for later delivery to help decide if putting your bushels on a basis contract would be a good plan. If the USDA does reduce corn yield in the November report, prices will rally and basis will widen.
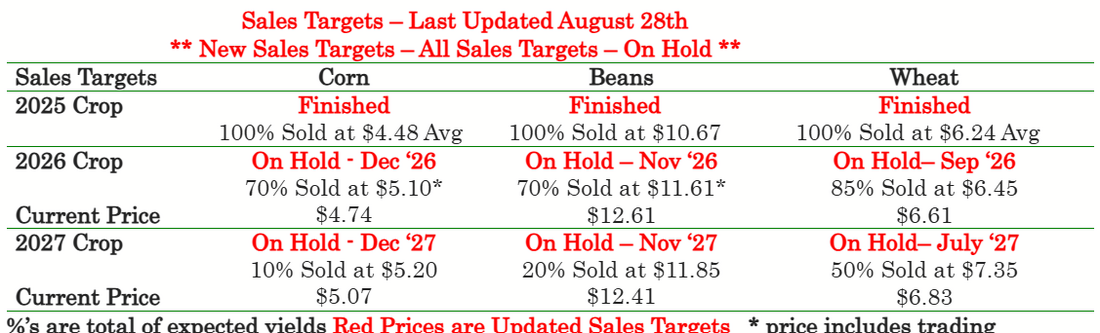
- The average fall insurance revenue prices are $4.90635 for corn and $12.83085 for beans. With more than half the month gone, the averages will not move higher with both Dec corn and Nov bean prices substantially below the monthly average. Another safety net pulled out from under on-farm income.
- Weekly Changes: Corn – 5 1/2 (Dec ‘26), - 30 3/4 (Nov ‘26), Wheat – 10 1/2 (Dec ’26), Crude + 956, Diesel +1607, Dow+288, US Dollar-364, Cattle+345, Feeder Cattle–195, Hogs-812, Cotton-54, Milk+29 (15.27).
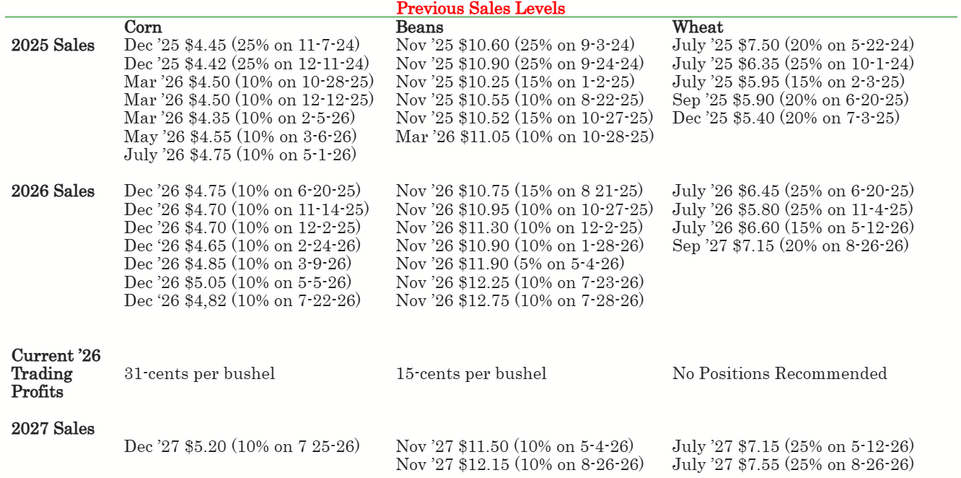
Disbelief of the USDA corn yield number was the most prevalent theme last week and while the USDA may be wrong, they are unlikely to admit it in the November 10th update so it might not be until the January report before Nebraska’s massive corn yield jump is addressed. Either way, the bearish news will do irreparable damage to farm budgets as the revenue insurance fall average will be too low to help in corn and all sales made because of a lack of storage will be locked in with few ways to recover that lost income. There are no immediately bullish factors to ignite a quick recovery and with early voting already started in most states for the mid-term election, the chatter about more government help for farmers and ranchers to buy your vote will be heard. Choppy with a bearish lean is my expectation for the markets into month end. Have a great Sunday.
December Corn – Weekly
November Beans – Weekly
December Wheat - Weekly
November Diesel – Daily
A Complete Overview of Current New Crop Market Conditions
Last Updated: 10/18/2026
Fundamentally
Technically
Short Term
Long Term
Volatility
Trade Rec
- Corn Neut/Bullish Bearish Neut/Bearish Neut/Bullish High None
- Soybeans Neut/Bullish Bearish Neut/Bearish Neut/Bullish High None
- Wheat Neutral Bearish Neut/Bearish Neut/Bullish High None
- Cotton Neutral Neutral Neutral Neutral Medium None
- Cattle Neut/Bearish Neut/Bullish Neut/Bullish Neut/Bullish High None
- Hogs Neut/Bearish Bearish Neut/Bearish Neutral Medium None
- Diesel Neut/Bullish Neut/Bullish Neut/Bullish Neutral High None
- Denotes positive change
- Denotes negative change
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.