
- Corn 8 to 9 ¼ higher
- Soybeans 12 to 13 ¾ higher
- Wheat 3 ¾ to 5 ¾ higher
- Basis Flat/Higher
- Live Cattle 265 lower (210.95)
- Dow Jones 142 higher (53,633)
- Crude Oil 266 lower (82.35)
- Feeder Cattle 495 lower (319.28)
Despite lower crop ratings on Monday, the overnight reaction was not overly bullish with beans continuing lower after Monday’s poor trade. But strong end user and speculative buying interest for the rest of the day sent prices higher with closes on the highs of the day. Wheat rebounded from early losses to post decent gains as the strength in corn and doubt for any resolution in the Black Sea will continue to find buyers of news-based breaks. Another flash bean sale was announced this morning to help confirm that China remains active while other end users are understanding that the US is on track to produce a billion less bushels of corn while total northern hemisphere grain loss could exceed 1.5 BBU including Europe’s drastic yield losses. Other than positioning around Monday’s September futures first notice day (which was last year’s harvest bottom), the trade remains supported by far more bullish news than bearish developments.
News and Notes:
- US weather forecasts remain seasonal for temperatures but leaning dry into the Labor Day holiday. El Nino continues to strengthen and with southern hemisphere planting starting soon, the historic trend of a Super El Nino is not good for trend line yields for SA and Australia.
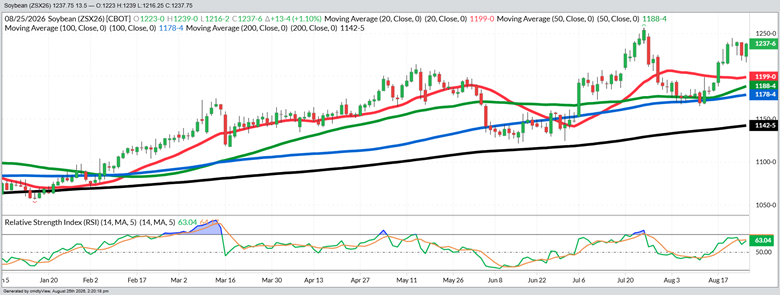
- The November daily bean chart is on Page 2 and shows the steady (but largely unexpected) uptrend for bean prices since the first of the year. The year has seen weather problems come and go, but the insatiable demand has been the constant to keep buyers under every meaningful break. When Brazil and Argentina harvested their record bean crops in late spring, there was no one that came out and confidently predicted that we would see new contract highs in August when the US bean crop still has trend line yield potential. It has been a hard year to confidently market beans.
- Monday’s crop ratings fell more than expected with corn falling 3% to 57 % G/E (the lowest in late August since 2023) while beans fell to 60%. The surprising number for corn is that 17% of the crop is in Poor/Very Poor condition to highlight the wildly inconsistent growing conditions across the Corn Belt. Too many states have deteriorating ratings and recent crop tours are confirming what many weekly surveyors have been reporting all season. The last time the ratings were this low the final yield was 4 ½ bushels under trend. This year, the losses from trend look to be nearly double that.
- There continue to be statements from Ukraine that “diplomatic” efforts are underway for a Black Sea port infrastructure cease fire, but Russia says there are not any plans on the table. Similarly, Iran says they are close to a deal with Oman (their neighbor across the Straits) that they have an agreement to control the Straits and are working on a plan to reopen. The US has not confirmed this completely unenforceable agreement between Oman and Iran, so basically, we have a bunch of meaningless rhetoric that still moves the markets. Neither war is close to ending.
- Cattle prices were sharply lower again today on fallout from the USDA announcement of 2 additional Mexican border entries for cattle, including the largest crossing that handles 40% of the Mexican cattle brought into the US. There is no market that is bullish enough to fight off a government that is determined to lower prices.
- China continues to chip away at their purchase pledge of US beans with two solid purchases each day so far this week. The Sep 24th trade meeting is still on to discuss AI and many other broader trade topics. Ethanol and bio-diesel margins remain stout which is keeping basis strong at ethanol plants and bean crush facilities. The demand story was not getting much attention until the US yield loss problem popped up, but now there is no way to ration the record global demand without prices high enough to ration supplies and shrink the profitable margins.
- The late price surge into the close hit the Dec '27 corn Sales Target at $5.20 for the first 10% of next year's crop and the first initial new crop sale over $5 in over 3 years. The closest upcoming Sales Target is for '27 beans (10% at $12.15) with the target just 12 cents above today's close. With this year's lower yields, please work on figuring out what % of your crops you really have sold.
Bull markets like daily (or at least weekly) big doses of fresh bullish news and this bull market continues to get supportive daily news to keep the breaks modest and the upside intact. Two-sided volatility was a major market factor in 2026, but the calm and consistent nature of the price breakouts since the August USDA report surprise shows that no one is panicking but slowly understanding that the lowest prices of the year could be well behind us. The Oct corn call spreads I advised earlier this month were sold today for an 18-cent profit and rolled up to the Nov 530-580 call spreads to act as both overhead price protection against previously sold bushels and “courage” calls to allow sales in a bullishly trending market with some upside protected.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 10% at $12.75 – Nov ‘26 20% at $7.15– Sep ‘26
- 70% Sold at $4.97* 60% Sold at $11.42* 65% Sold at $6.24
- Current Price $5.24 $12.38 $6.86
- 2027 Crop On Hold - Dec ‘27 10% at $12.15 – Nov ‘27 25% at $7.55 – July ‘27
- 10% Sold at $5.20 10% Sold at $11.50 25% Sold at $7.15
- Current Price $5.22 $12.03 $7.29
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
November Beans - Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- September $5.01
- December $5.24
- March $5.39
- July $5.47
Beans
- September $12.28
- November $12.38
- March $12.58
- July $12.68
Wheat
- September $6.86
- December $7.03
- March $7.21
- July $7.29
Other Closes
- Oct Diesel 4.1339 -395
- Dec Cotton 88.34 -49
- Cash Cattle $228 Offer
- Lean Hogs 80.45 -68
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.